Why RWE retreated from merchant power risk
RWE's pullback from merchant exposure reflects structural shifts in how renewables operators manage commodity price volatility
At a Glance
- RWE has stepped back from direct merchant power market exposure, signaling a strategic reorientation
- Merchant risk management remains central to renewable energy business models as capacity deployment accelerates
- Long-term contracting and hedging strategies are replacing traditional spot-market reliance across the sector
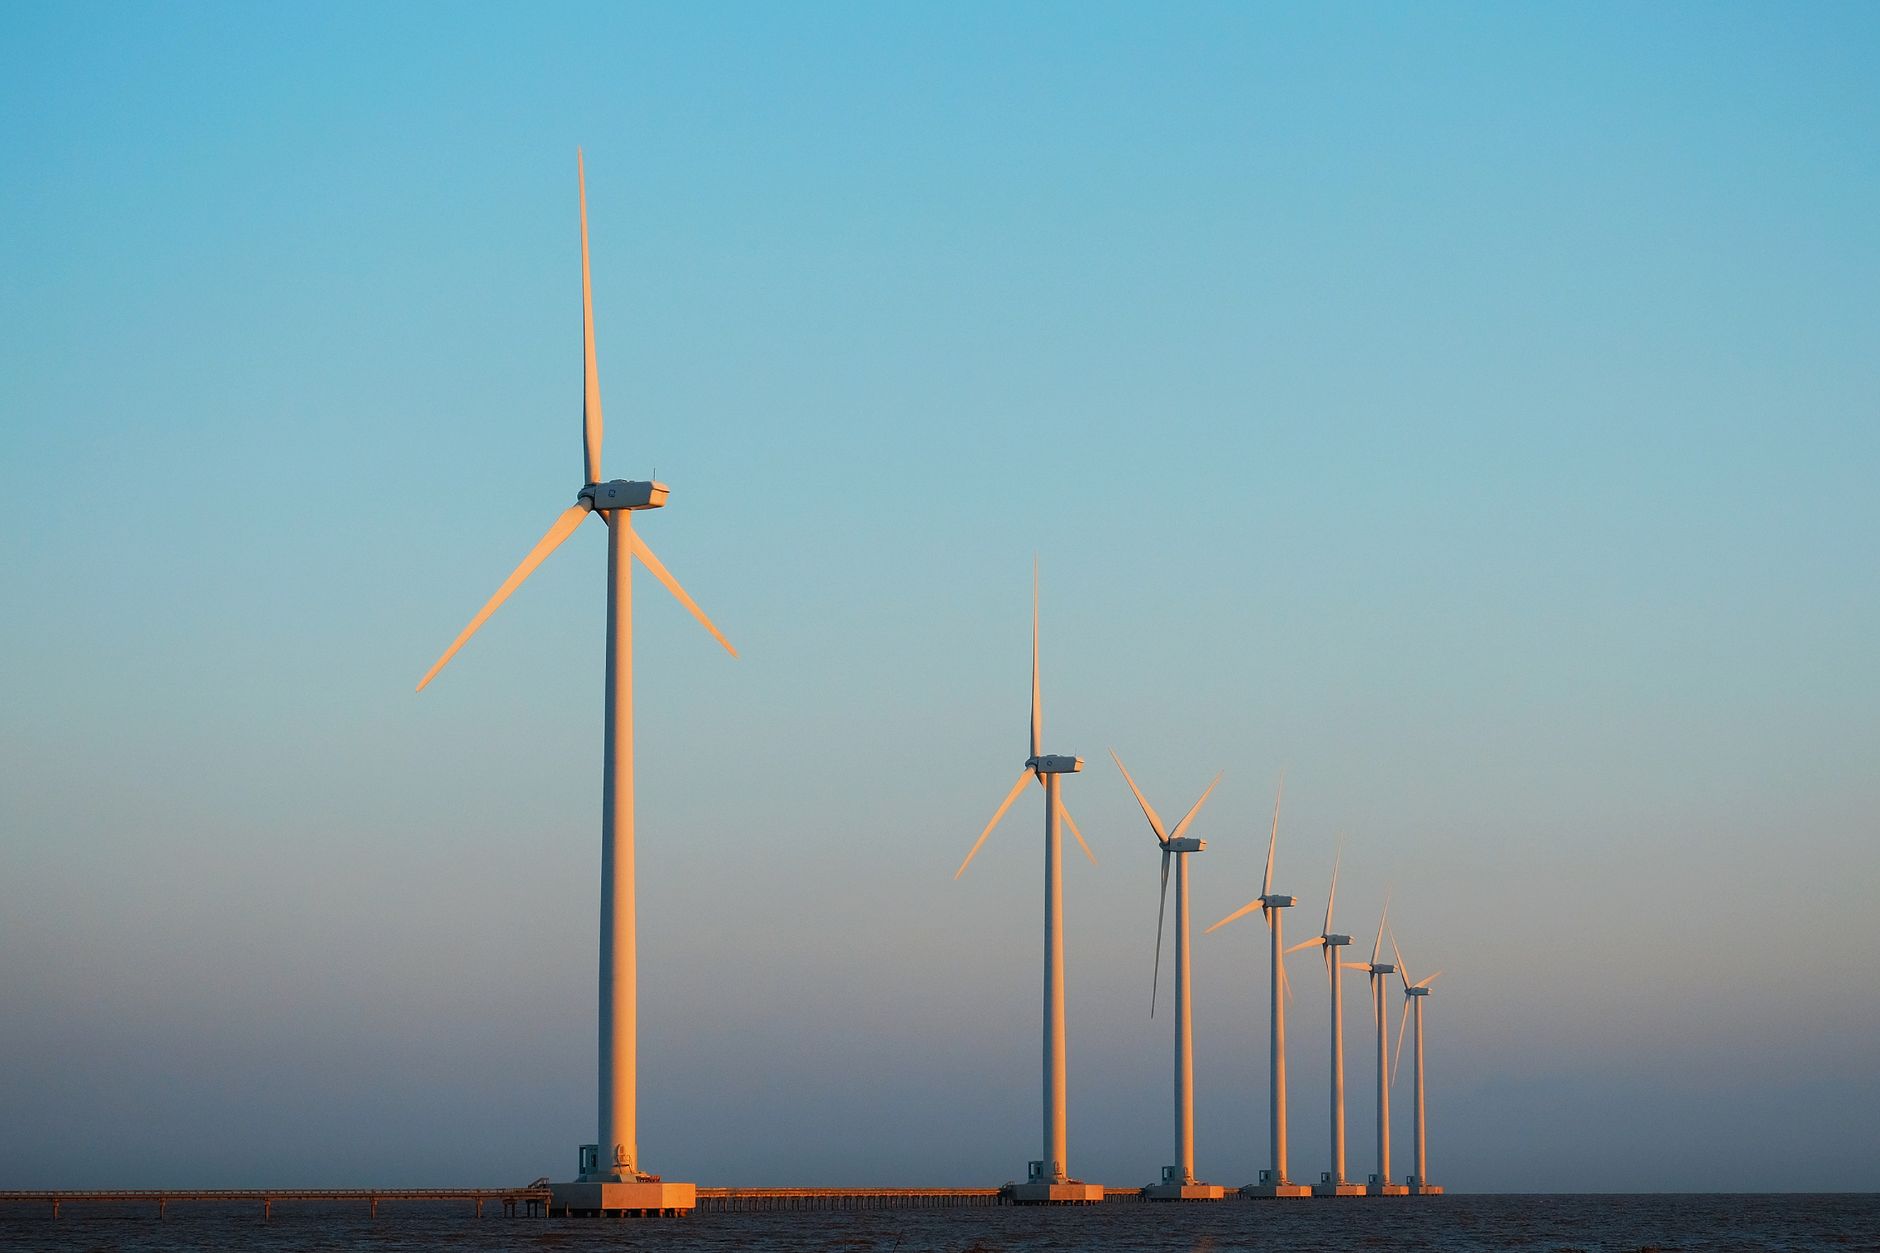
- Modern offshore turbines with 115-meter blades amplify the importance of stable revenue streams to justify capital deployment
The Mechanics of Merchant Risk
Merchant exposure—betting on wholesale electricity prices without long-term contracts—works when you can absorb margin compression. But scaling renewable capacity changes the equation. When gigawatts of new wind and solar come online regionally within months of each other, price suppression becomes predictable rather than theoretical. RWE's withdrawal from direct merchant positioning reflects this reality: the math on unhedged renewable projects stops working as the grid's clean-generation share climbs.
Capital Discipline in a Changing Market
Utility-scale renewable operators face a timing trap. Modern offshore turbine blades now routinely exceed 115 meters in length—exceeding a football field—which means individual units are generating enormous incremental output. That scale requires committed buyers, not speculative price exposure. RWE's move toward contracted generation aligns with this physics: you cannot justify billion-euro capex on blade hardware and foundation work if you're gambling that regional spreads stay wide enough to cover debt service.
Why This Matters for Project Development
The shift away from merchant risk doesn't mean renewables are becoming less competitive. It means the sector is maturing into structures that mimic conventional generation: fixed revenues, predictable cash flow, acceptable returns on deployed capital. This favors players with balance sheets and offtake agreements. For independent developers, it means corporate PPAs and government contracts become table stakes rather than nice-to-have. Pure merchant plays now require either exceptional storage capability, geographic diversity, or acceptance of returns that institutional capital won't underwrite.
Implications Forward
RWE's repositioning is not a retreat from renewables—it's a retreat from the illusion that unhedged renewable generation can behave like dispatchable fossil capacity. As the European fleet continues scaling, expect more operators to tighten their hedging ratios and lock in longer contract terms. The wind resource isn't going anywhere. The commodity risk profile, however, is being actively managed out of the sector's core strategy.
Enjoyed this one?
Get the next MW Daily entry straight to your inbox.
mwdaily.energy — no spam, unsubscribe anytime